

US economy is having an extraordinary growth after the pandemic, leading all the G-7 nations by far. The wage and productivity growth is good, inflation is flattening, the labor market is great, actually the best in many decades. The economic growth is coming with strong investment in productive industrial areas. This might be a new growth story if US can sustain it at least for this decade. How did it came about?
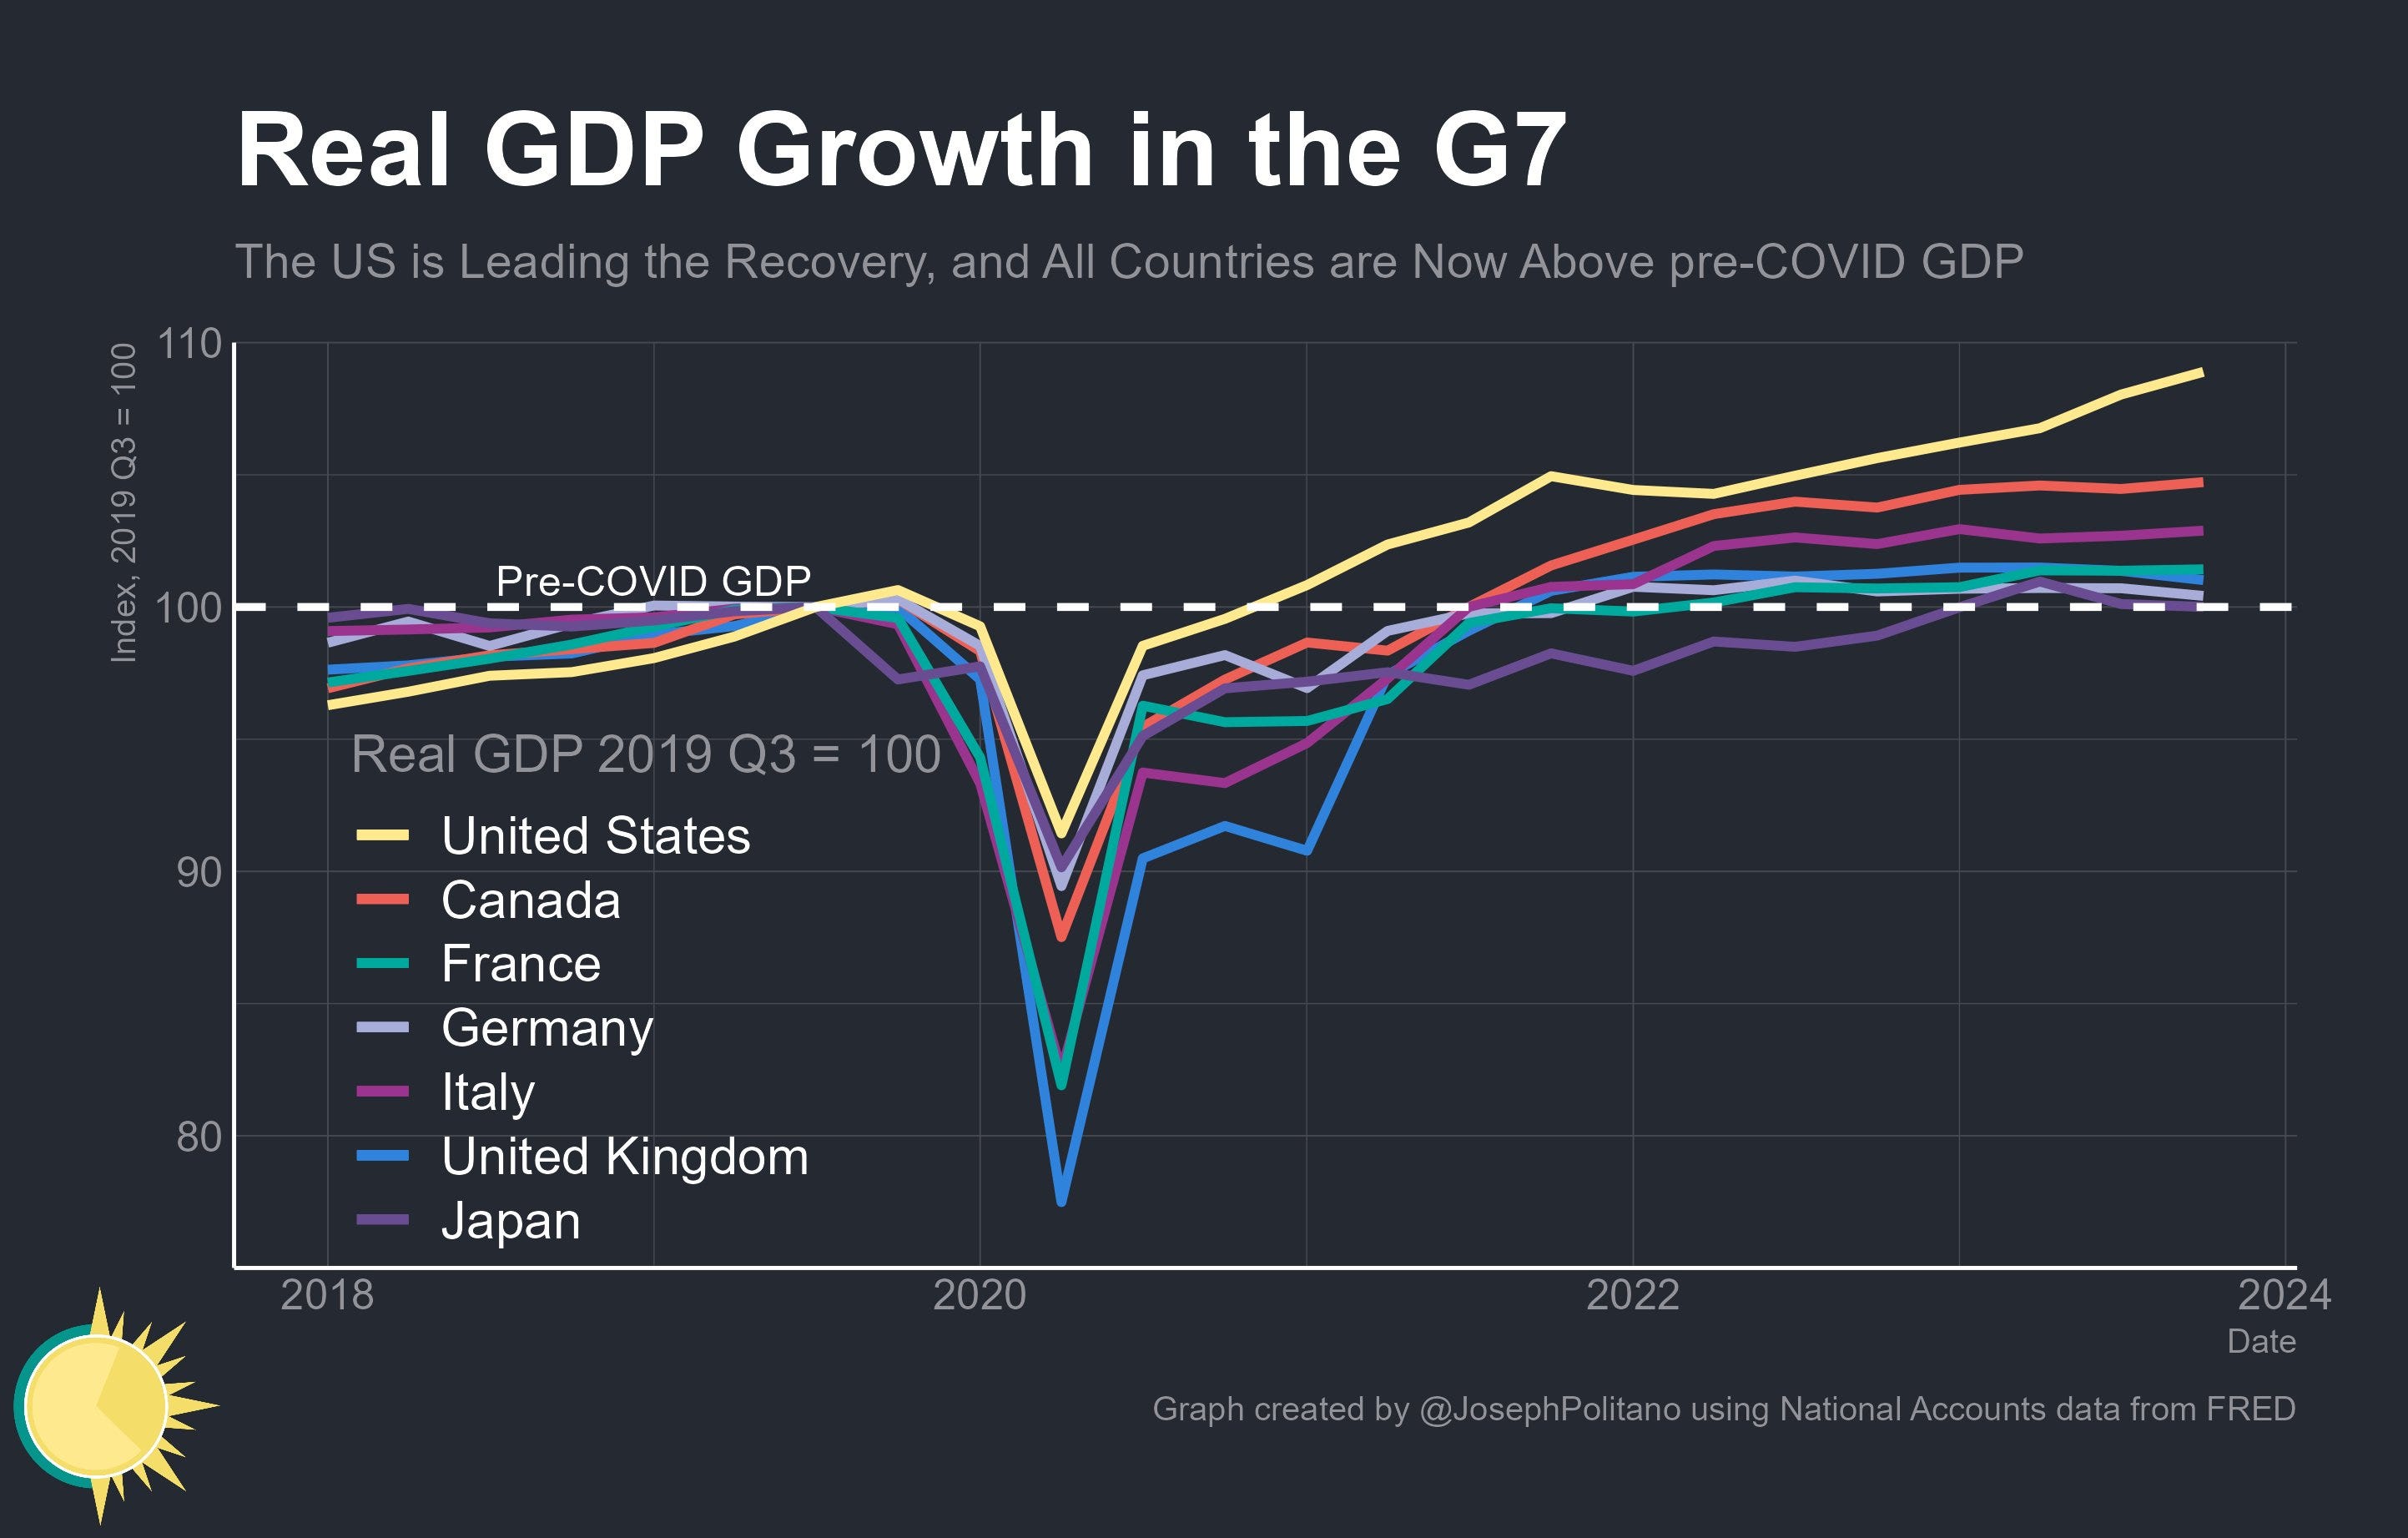
US leads the G-7 in post pandemic growth
It started with the big fiscal of pandemic era - go big or go home, the idea of Dem Party when it won 2020 elections. This was American rescue plan which rescued the “main street” with various financial support programs to people, stabilized demand and economy in 2021 during unprecedented uncertainty of pandemic. There was also big support provided to Wall Street by federal government and central bank. Then with 2022 and 2023, more fiscal policies came in form of Infrastructure Bill, Chips and Science act etc to build public infrastructure, promote industrial investment in America especially in high technology areas with massive subsidies.
What is big fiscal? It’s not just big tax cuts, trickle down policy and directionless subsidies to private sector. It’s channeling of fiscal support to nurture specific development for specific purpose - the so called industrial policy.
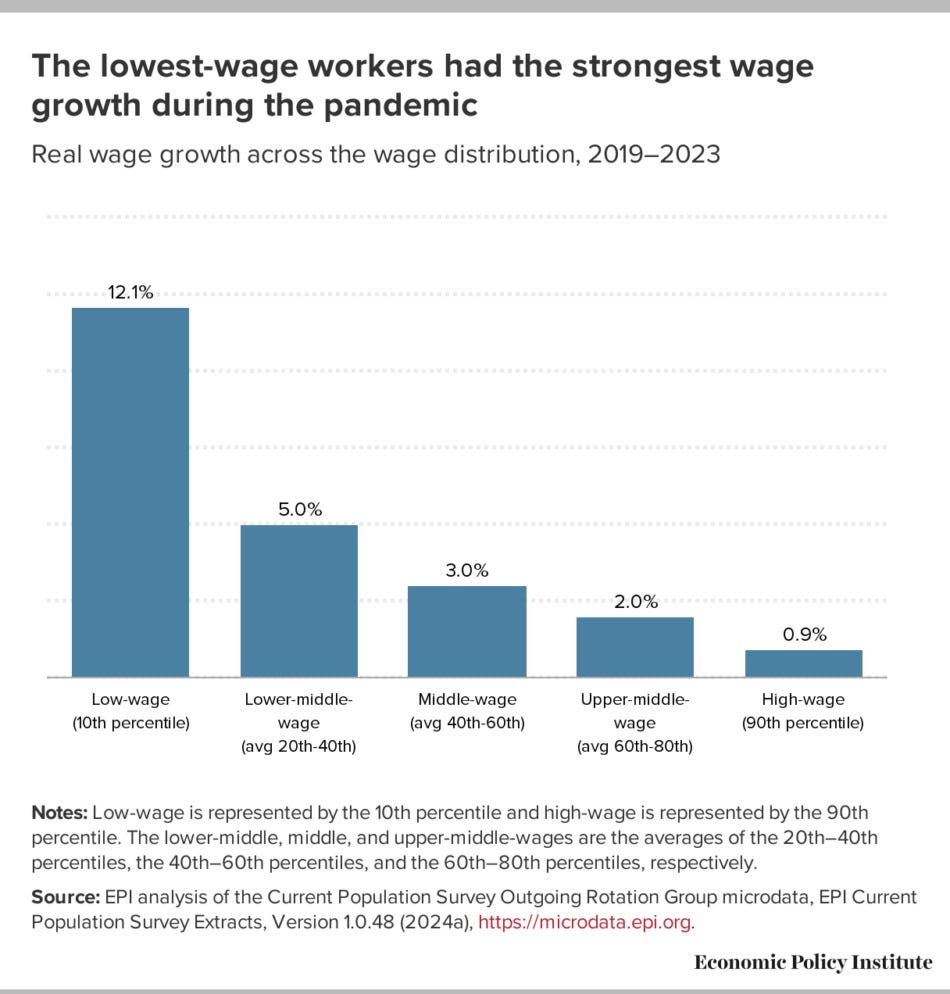
The growth and wages data is good and (dis)inflation data is on right track. What do experts fear for? A Shock that will derail this growth story. What we are in is a sweet spot of economy and this trend should be maintained. Experts primarily are fearing Fed interest rate shock since last year. Fed started to hike interest rates to respond to inflation. The rise of inflation was primarily driven by extraordinary supply shock of once in a century pandemic & later Ukraine war. But certain people, the Neoclassical Nihilists, picked up their old textbooks and start preaching about return of 1970s. They demanded high interest rates to create a recession, create army of unemployed and to squash the wage-price spiral (which didn’t exist).
With early 2022, the end of pandemic was in sight as sufficient Vaccines were developed, mass produced and dispensed. The saner macro voices knew that supply shocks of pandemic are about to be resolved and there is no need to refer the Volcker’s 70s playbook. The economic data during pandemic era were not “normal” trends. A better policy would be to wait and watch how economy re-adjusts (re-combobulate) to certain normalcy. The Fed rate hikes were aggressive and experts forecasted a recession. The Neoclassical Nihilists prophesied this decade with long recession and stagnation. Even the team-transitory feared that such rate hikes may derail the growth story but recession is not an inevitability. Saner economists do not subscribe to solving inflation problem with recessions.
Recession however didn’t happen. The inflation came down and team-transitory wanted to to ease interest rates. The causes of inflation are complex and commodity inflation is significantly influenced by global factors and often supply disruptions (Climate change, wars, pandemic, sanctions etc). However, central banks still follow the old textbook of rate hikes to manage inflation as a demand side problem. Monetary policy is also used as a balancing tool between credit inflation and commodity inflation. Higher interest rates cause higher cost of home loans, auto loans, personal loans etc and also business loans & cost of raising Capital for entrepreneurs. Higher interest rates is used for transferring pain in legs to pain in arms. A jugglery that is supposed to evenly spread the pain somewhat. Not much thinking is put into the source of pain or whether if placebo medicine of rate hikes is even necessary.
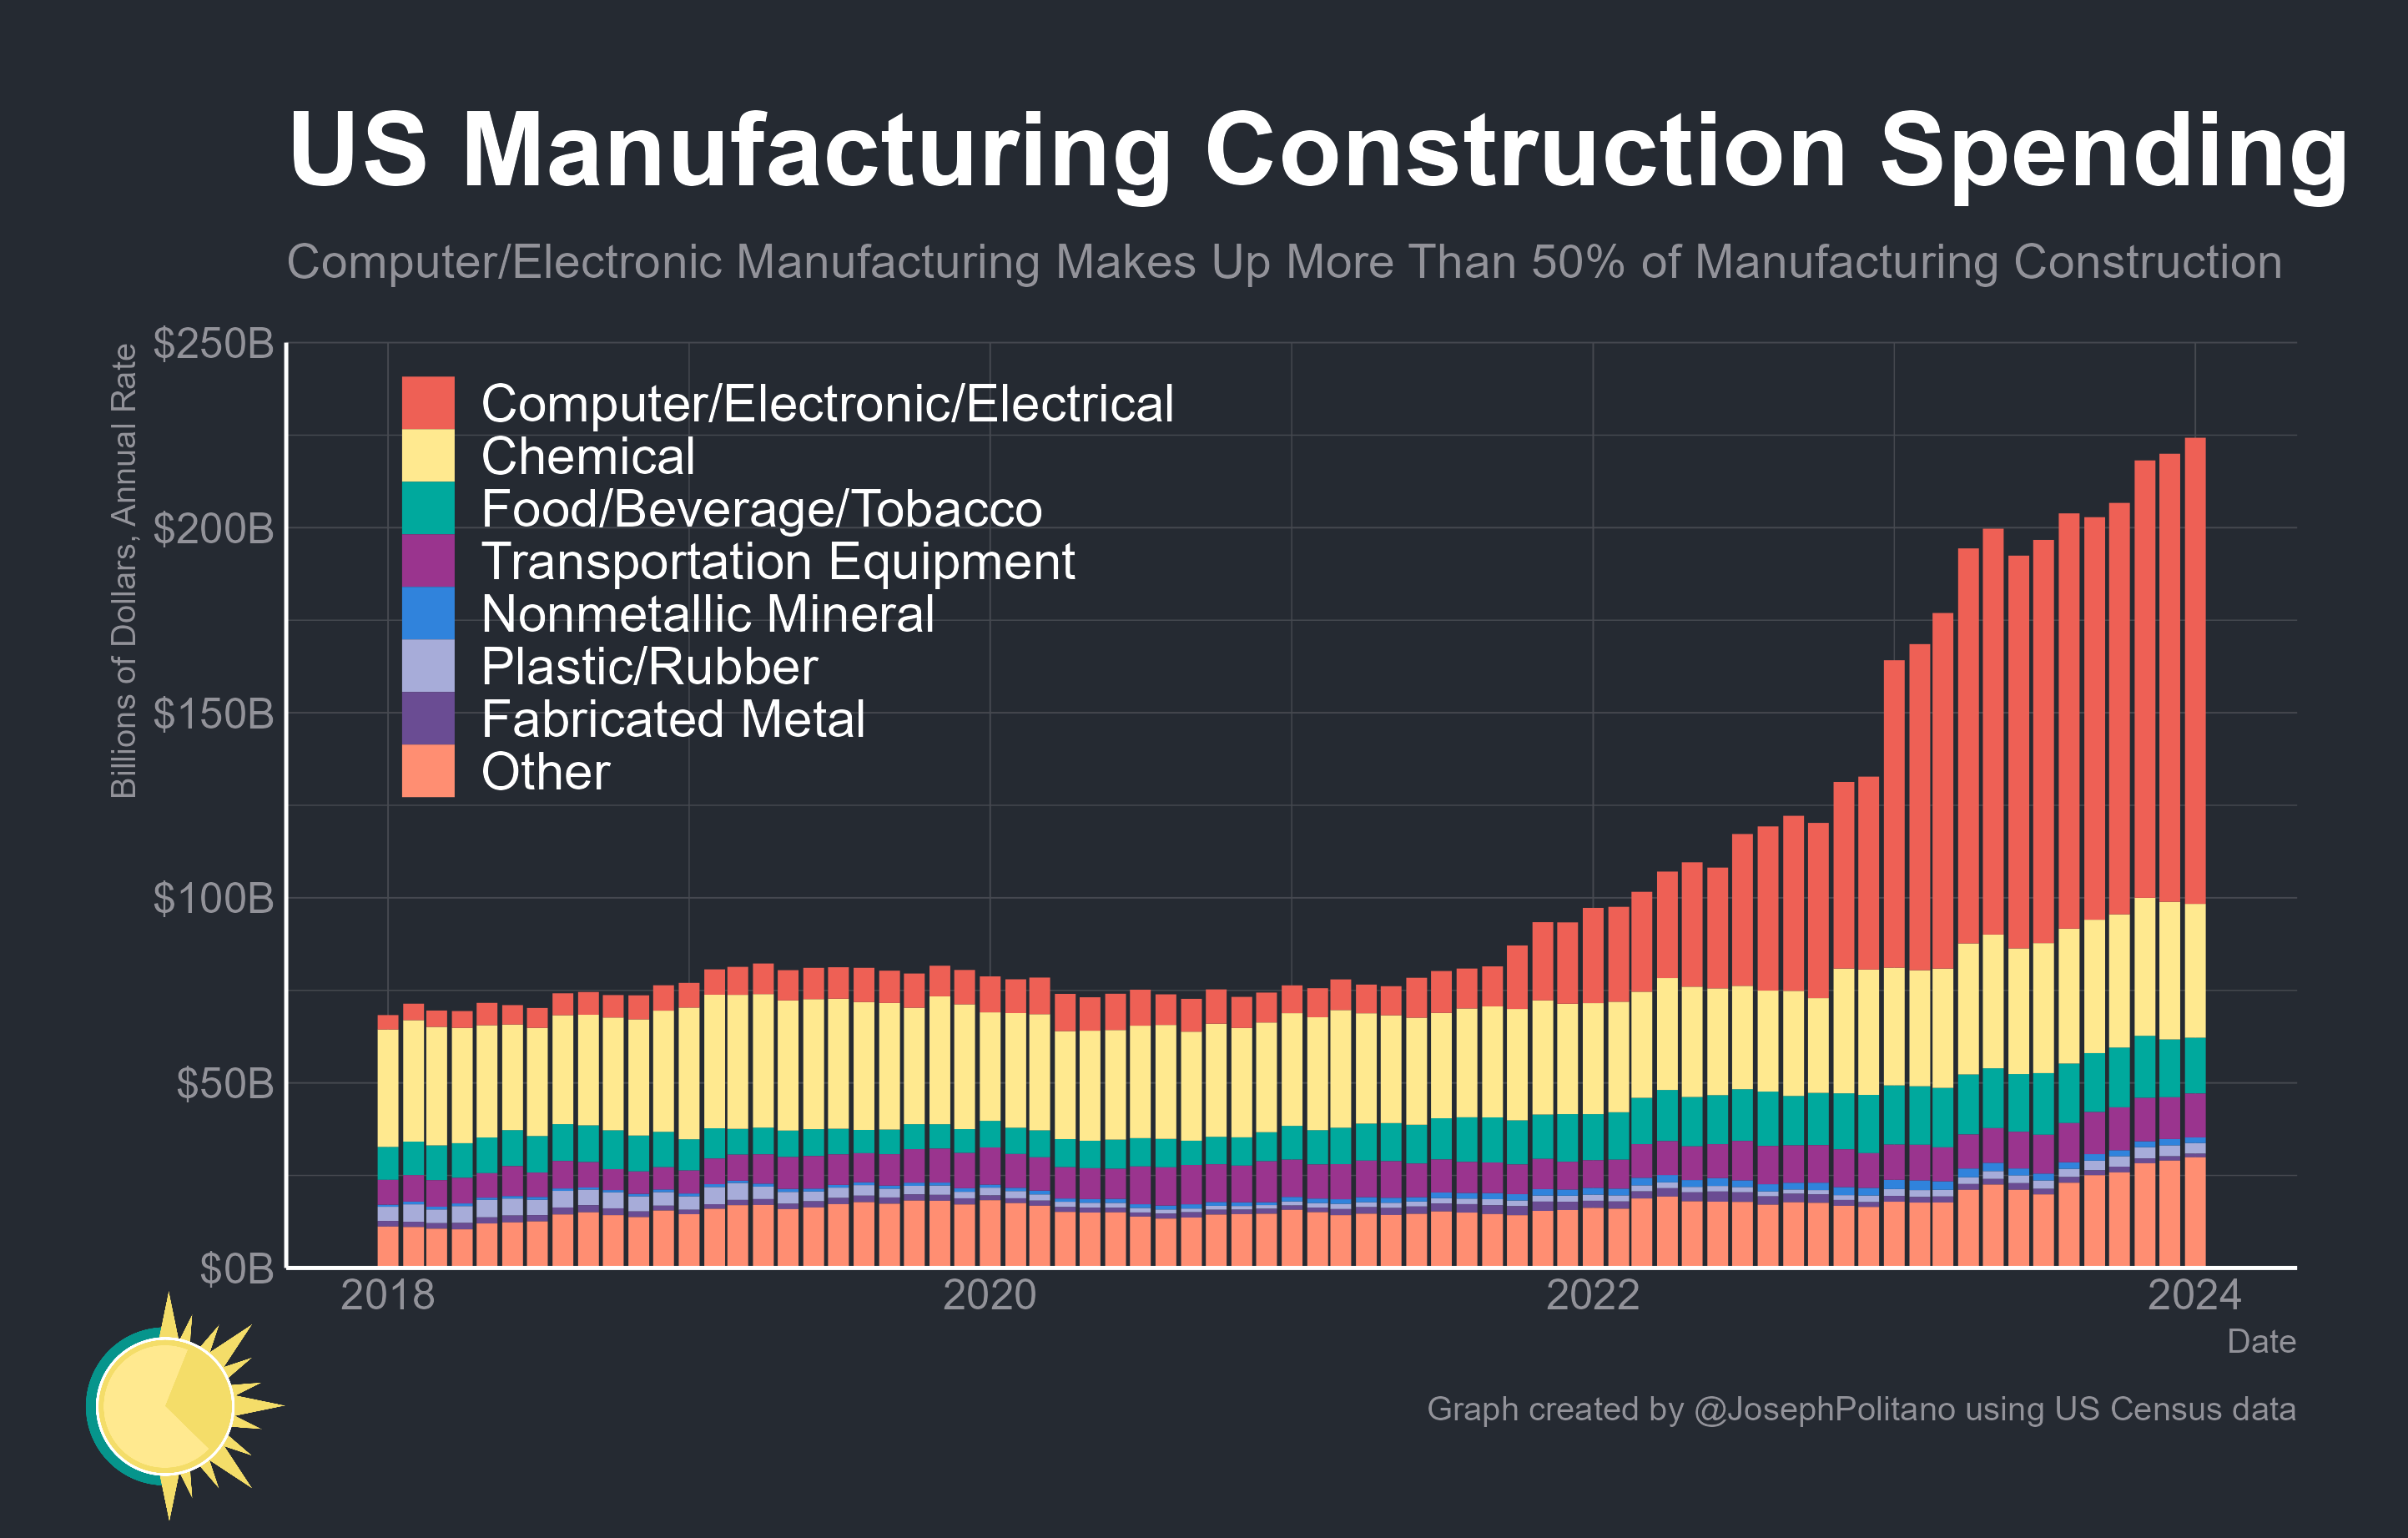
The semiconductor Industry boom in America
Higher interest rates are a deterrent to growth as it burdens consumers with higher payments on debt and constrains entrepreneurs in Capital investment. But interest rates are not the only factor that determine growth. Big Fiscal sustains demand and propel investment. Fiscal policy also brings certainty and direction to economy. For example, the businesses today know that government is firmly backing the development of domestic semiconductor industry so businesses can make their long term investment decisions with confidence in this area. Then there’s more good with overhauling of infrastructure and green energy transformation that provide structural strength to US economy. This is contrary to trickle down tax cuts to the rich fiscal policy (2017) that produced no results.
The higher interest rates did produce some troubles in financial sector but Fed and US Govt, for better or for worse, are always there to rescue the failing institutions (SVB, First Republic etc). The damage was contained (tech brothers got their deposits back) and financial sector doesn’t show signs of any significant stress.
Two question arises. Can we do better than present if the rates go down? Will lowering cost of borrowing, boosting demand and more investment can create even better economy? Or will it overheat the economy? We don’t know. Secondly, are there are any signs of stresses in economy due to higher rates or are higher rates starting to pull down economy? Here Fed is said to be data driven and keeping a hawk eye on economy.
The goal of central bank is to nudge the economy towards a path. Experts call it with various names (more like misnomers) - the goldilocks economy, the equilibrium, the natural rate (if it really exists). If interest rates start becoming a drag on economy, central banks have to cut. If fiscal policy is needed to sustain effective demand in economy or strategic investments have to be made, that Govt needs to spend accordingly. There are variety of factors that influence the state of economy including globalized factors and factors that are not explicitly identifiable. The combination of all these factors determine the sweet spots of economy and there can be multiple such points. However, once you have the momentum of growth on your side, you really resist trying something different.
Who knows that with lower rates and more big fiscal (especially on public housing and Green transition) we may have an economy into a better (sweeter) spot? But Fed is historically a conservative institution that significantly weighs past trends to make its present decisions. The idea of making a move on rates and inflation data coming bad is dreaded by the Fed. The reasons for bad data can be several but Fed may bear the blame for “moving too early”. Hence Fed delays the decisions on rates with an excuse of “waiting for more consistent data”.
The holy grail of 2% inflation also seems to be arbitrary. Inflation is bad for both economic and political reasons. Economic agents want price stability as it gives them more certainty for making investment and spending decisions, and planning contracts in general. Too much price volatility and economic agents have hard time making rational decisions and creating stable contracts. Inflation can also be a political fireball as Politicians usually exaggerate the issue and people also have strong bias against price rise issue. However, there are other problems that also must be dreaded like a recession and high unemployment, even more dreaded should be when it’s created artificially in quest for killing demand and solving inflation.
A better approach should be a narrow band of inflation target, like 2%-3% which can be treated as a benchmark. This can give more breathing space for Fed and better policy planning for Govt.