

Keynesianism was the macroeconomic security of business cycles in golden years - from late 1940s to late 60s. Fiscal intervention to manage effective demand was hailed as crucial instrument to achieve economic stability & growth in western world. It was three decades of strong industrial, social and economic progress up until the wage price spiral, Oil shock and stagflation of 1970s (the breakdown of Philips curve). Then Neoliberalism emerged where monetary policy was made the holy grail to stabilize business cycles. It was not a genuine stability as social balance diminished and interests of financial markets were put above socioeconomic interests of labor & its bargaining power.
After the draconian rate hikes of Volcker and moderation of inflation, the central banks and interest rates were normalized as dominant tool to guide economy. At the same time, the fiscal austerity (and other mantras of Washington consensus) became a bitter medicine for achieving price stability and growth. The inequality surged in this era and the too big to failed transnational institutions emerged. The central banks managed business cycles by various tools and cheap liquidity while deregulation & de-supervision became the norm in later years of great moderation era. The belief was that a systemic crisis can’t occur, central banks can always foresee & control a crisis ( after all central banks did manage to smooth out some economic aberrations in this period). Then came the Minsky moment that blew up everything.
Even in the great recession of 2008, things were not cataclysmic. The central banks used various liquidity programs to rescue too big to fail institutions and financial markets. Most of the financial system and its institutions were thus preserved. The government backstopped wall street while same attention was not given to ‘mainstreet’. However, the old tools of social protection (automatic stabilizers like unemployment benefits) still ensured that there remained some floor under the economy. Due to fiscal austerity (debt & deficit phobia) there couldn’t be fast enough recovery and we had long term unemployment but still the crisis was not nearly as severe as of last century’s great depression. Even within Neoliberal system, there were some remnants of Keynesianism that served their purpose well for society.
To my surprise, US government learned lessons from slow recovery of post GFC era. So when Covid induced recession came, the government fired on all cylinders to protect the economy - Wall Street as well as main street. While central bank used its tools for saving the capitalist ecosystem (large QEs, global swap lines, flooding markets with liquidity etc), the government used aggressive fiscal policy to sustain average people through widespread income support programs. The US government (that includes central banks) response to pandemic recession is a charming success story. And beyond that, there was return of sophisticated industrial policy to nurture strategic sectors of economy. And we also managed to beat inflation which otherwise old neoclassical Nihilists wrongly claimed that it would haunt US for long years and we must create a recession to avoid repeat of 1970s.
All this had me thinking that there might emerge a new great moderation (call it version 2.0). Success of ‘big fiscal’ was making a comeback, at least some of the mantras of Neoclassical & laissez-faire thinking were losing credibility and the era of government intervention to aggressively participate in economy (when & where it’s needed) was back. The quality of technocrats (remember Lina Khan?!) and politicians also improved in this period. US economic growth, wages, productivity and unemployment - all data got rosy. So given all these things, i thought that governments have become smart & sensible enough to deal with any major economic crisis. The business cycles will be more stable and there will be lower uncertainty on economic discourse. Then incomes Donald Trump.
Under Donald Trump, the competence of central banks is becoming irrelevant. No amount of forward guidance and monetary policy optimization can cure Trumpian uncertainty. Even in usual times, central banks hardly have much control over prices, and with Trumpian supply shocks, Fed cannot do anything about them. So one crutch of economic stability - the central bank competence - is rendered useless (this crutch will be broken if Trump fires Fed Chairman). The other crutch was broken deliberately. The Weberian institutions of government were dismantled, competent people were fired, regulatory institutions were closed and minions were installed in critical institutions. Arbitrary budget cuts and deficit reduction is launched in name of achieving ‘governmental efficiency’ as if government is a private enterprise.
Donald Trump is probably the most disturbed & unstable person on this planet. His policy ideas (or more accurately his daily whims) changes by every day & every hour. He will wake one day with any arbitrary number in mind and declare that it should be tariff on so & so nation. There’s no deliberation & technocratic process to government functioning anymore. Now what will happen?
The quest for certainty was the idea behind great moderation. The business cycles will always be managed. There will always be a good degree of certainty for businesses to make their investment decisions and consumers to plan consumption. There won’t be wild swings in economic variables. The economic & trade policies and government regulations will be predictable and mostly conducive to economic activity. The foreign relations with other nations will be managed competently - after all we are in globalized economy. The central banks and government institutions will keep a close watch on economy & will always have variety of tools to make interventions when & where needed.
But when the very foundation of competent national leadership is destroyed, there can’t be any stability in economy. I am actually puzzled how the markets so far remain stable. I mean we had some major gyrations & volatility in markets but that still doesn’t fully reflect the craziness of the situation. The markets remain out of touch with reality for two reasons. Markets are processors of conventional wisdom (this terminology comes from Nathan Tankus) and Donald Trump is still believed to be a conventional President (this is due to all the sanewashing and truthwashing by media).
The markets & economic agents, the business community haven’t fully grasped various aspects of Trumpian chaos. For example, one aspect of dollar crisis which markets don’t comprehend is the crisis of ‘finality of currency payment’. With DOGE arbitrarily stopping federal payments through governmental digital payment systems, the basic concept of settlement of currency transactions is put into question. Markets don’t heed to this brewing crisis. The fact that payment on a legitimately authorized government program can be dubiously revoked is a dangerous situation.
Secondly and more worrisome reason is that the financiers, tech billionaires and Wall Street elites themselves are out of touch with reality. They created & nurtured the Frankenstein’s monster of Donald Trump. Why? Will the giant tax cuts, deregulation, privatization and crony special favors be worth more than the chaos & economic destruction caused by Donald Trump? While Trump is a disturbed & unstable man, he’s propped up by people like Elon Musk who are also unstable & delusional. Meanwhile, the sanewashing & truth washing by media continues. Trump regime continues to execute insane policies which in a normal world would have raised flashing signals of 5 alarm fire.
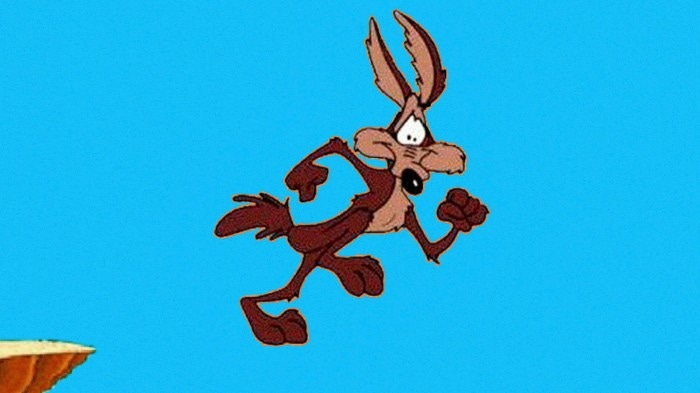
So, are we in a time like that Roadrunner cartoon where Coyote runs past the edge of the hill and continues to take some steps before the gravity catches up to him?
Musical coda
For the sake of clarity, erhaps my question is best boiled down to asking why the focus on Trump rather than, say, Berlusconi. Why not call Trump a "Berlusconi like" figure? Focusing on the Italian experience allows for clearer insight into the alignments of the day, the conflicting political cultures and trajectories. Incidentally, one could also start with Farage and Brexit. From this perspective and with respect to Trump, the insistence on centring of the analysis on Trump highlights how critique itself can prove complicit with the restatement and reinforcement of American hegemony. I am just not sure that these different starting points yield the same outcomes. This, I suppose, is my conundrum.
Thank you for an exhaustive and very interesting discussion of Trump's return to the presidency of the United States. I am perhaps grabbing the wrong end of the stick, but I find the account strangely insular. In my view Trump's emergence is the latest instantiation of a more general, global phenomenon and this is the context in which it needs to be examined. Borrowing from physical chemistry, I regard Trump as the perturbation that precipitates a phase change, a qualitative change in the state of matter. Trump is the endpoint of a global, secular process of transformation, involving both the emergence of a neoliberal governmental apparatus and the end of the Cold War. New state actors have emerged, the EU, the BRICS and the PRC, but perhaps with the exception of the latter, the state is increasingly redundant, except perhaps as a guarantor of negative freedom. Plutocracy has everywhere captured the geopolitical apparatus and in a way that calls into question whether we are not in fact witnessing the end of capitalism. Going back to Foucault's Order of Things, the intellectual challenge of the day I think is to articulate the new grammar and syntax of power. This is what I meant when I expressed uncertainty about where we are in the play of difference and repetition. Anyway, hard as it may be, we need to decentre Trump and the US. Only then will we be able to start making sense of the new state in which we find ourselves.